
What Drives Home Insurance Premiums: Key Factors
Understand the factors that affect home insurance premiums and take control of your costs. Call (833)-214-6397 for expert guidance.
By Olivia Adler
Your home insurance premium is not a random number. It is a calculated reflection of the risk an insurer assumes when they agree to protect your property. Understanding the factors that affect home insurance premiums gives you leverage to make smarter choices, potentially saving hundreds of dollars each year. Whether you are buying your first home or reviewing your policy at renewal, knowing what drives costs helps you anticipate changes and take action to keep rates manageable.
In this guide, we break down the most significant variables that insurers use to set home insurance rates. You will learn which factors are within your control and which are simply part of your home's profile. We will also share practical steps to improve your risk profile and lower your premiums without sacrificing coverage. If you are ready to compare personalized quotes, you can start by visiting InsuranceShopping.com to explore options from multiple providers.
Location, Weather Risk, and Proximity to Fire Stations
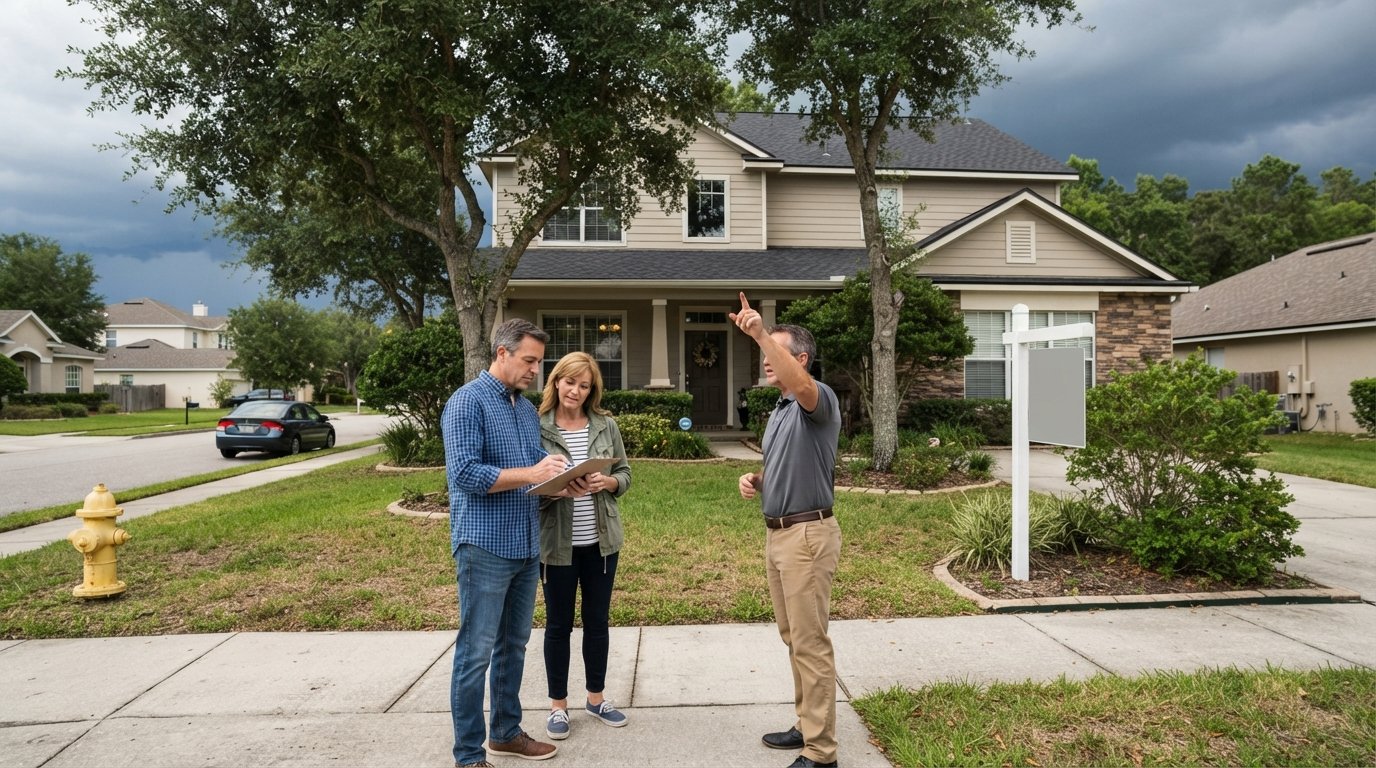
Where your home sits is perhaps the single largest factor in determining your home insurance premium. Insurers assess regional risk based on weather patterns, crime rates, and the availability of emergency services. Homes in areas prone to hurricanes, tornadoes, wildfires, or flooding carry higher premiums because the likelihood of damage is greater. Even within the same city, your specific neighborhood matters: a property in a flood zone or on a fault line will cost more to insure than one on higher, drier ground.
Proximity to fire stations and fire hydrants also plays a crucial role. If your home is more than five miles from a fire station or lacks a nearby water source, insurers may charge more because the potential for severe fire damage increases. Some companies offer discounts if you live within a certain distance of a professional fire department. If you are considering a move, it pays to check the fire protection classification of the area before you buy.
- Weather exposure: Coastal properties, hail-prone regions, and wildfire zones typically face higher premiums.
- Crime rates: Areas with higher property crime may see increased rates due to theft risk.
- Fire protection: Distance to a fire station and hydrant availability affect rates.
- Local construction costs: Areas with high labor and material costs may have higher premiums to cover rebuilding expenses.
While you cannot change the weather, you can sometimes mitigate its impact. For example, installing storm shutters or impact-resistant windows may qualify you for discounts. Similarly, adding a monitored security system can offset some of the risk associated with crime-prone areas. Always ask your insurer about location-specific discounts before you finalize a policy.
The Role of Home Age, Roof Condition, and Construction Materials
The physical characteristics of your home tell insurers a lot about how likely it is to sustain damage and how much it would cost to repair. Older homes often have unique features that are expensive to replace, such as custom woodwork or antique fixtures, and they may have outdated electrical, plumbing, or heating systems. These factors increase the risk of fire, water damage, and other claims, leading to higher premiums.
Roof condition is particularly critical. A new roof with impact-resistant shingles can significantly lower your premium, while an aging roof near the end of its life may raise red flags for insurers. Some companies require a roof inspection before issuing a policy. Construction materials also matter: brick homes tend to have lower premiums than wood-frame homes because they are more resistant to fire and wind. Similarly, homes with updated wiring and plumbing are viewed more favorably.
If your home is older, you might still secure reasonable rates by making strategic updates. Replacing an old roof, upgrading the electrical panel, or installing a modern water heater can demonstrate to insurers that you are managing risk. Be prepared to provide documentation of these improvements when you apply for coverage. In some cases, the savings from these upgrades can offset the cost of the renovations over time.
Claims History and Credit-Based Insurance Scores
Your personal claims history is a direct reflection of how you have used your insurance in the past, and insurers use it to predict future claims. A pattern of frequent claims, even small ones, can signal higher risk and lead to increased premiums. Many companies offer a claims-free discount, which rewards homeowners who have not filed claims for a certain number of years. Think twice before filing a claim for minor damage; paying out of pocket may preserve your discount and keep your long-term costs lower.
In most states, insurers also use a credit-based insurance score to help determine premiums. This score is derived from your credit history but is not the same as your credit score. Studies have shown a correlation between credit behavior and the likelihood of filing insurance claims. A higher insurance score generally translates to lower premiums. To improve your score, focus on paying bills on time, reducing outstanding debt, and avoiding unnecessary new credit applications.
It is important to note that some states restrict or prohibit the use of credit information in home insurance underwriting. If you live in one of those states, your credit history will not affect your premium. Regardless of where you live, maintaining a clean claims record and healthy credit profile is a smart financial habit that can pay off in lower insurance costs.
Which Factors Homeowners Can Change and Which Are Fixed
Not all factors that affect home insurance premiums are within your control. Understanding the difference helps you focus your efforts where they matter most. Fixed factors include your home's location, age, and construction type; you can't move your house or change its building materials without significant investment. However, you can often mitigate the impact of these fixed factors through discounts and smart policy choices.
Changeable factors include your coverage limits, deductible, claims history, and credit-based insurance score. Raising your deductible can lower your premium, though you will pay more out of pocket if you file a claim. Improving your credit and maintaining a claims-free record can also reduce costs over time. Additionally, installing safety and security devices, such as smoke detectors, burglar alarms, and water leak sensors, can qualify you for discounts. Some insurers offer discounts for bundling home and auto policies, so it is worth comparing bundled quotes.
To make the most of these opportunities, consider a proactive approach. In our guide on ways to lower home insurance costs without cutting coverage, we explain how to identify discounts and adjust your policy strategically. By taking control of the factors you can influence, you can keep your premiums affordable while maintaining solid protection for your home and family.
Remember that insurance is a competitive market. Insurers weigh these factors differently, so the same home might receive wildly different quotes from different companies. That is why comparison shopping is essential. Use QuoteComparison.com to request quotes from multiple carriers and see how your home's profile translates into real-world pricing. With the right information and a bit of effort, you can find a policy that fits your budget and your needs.