
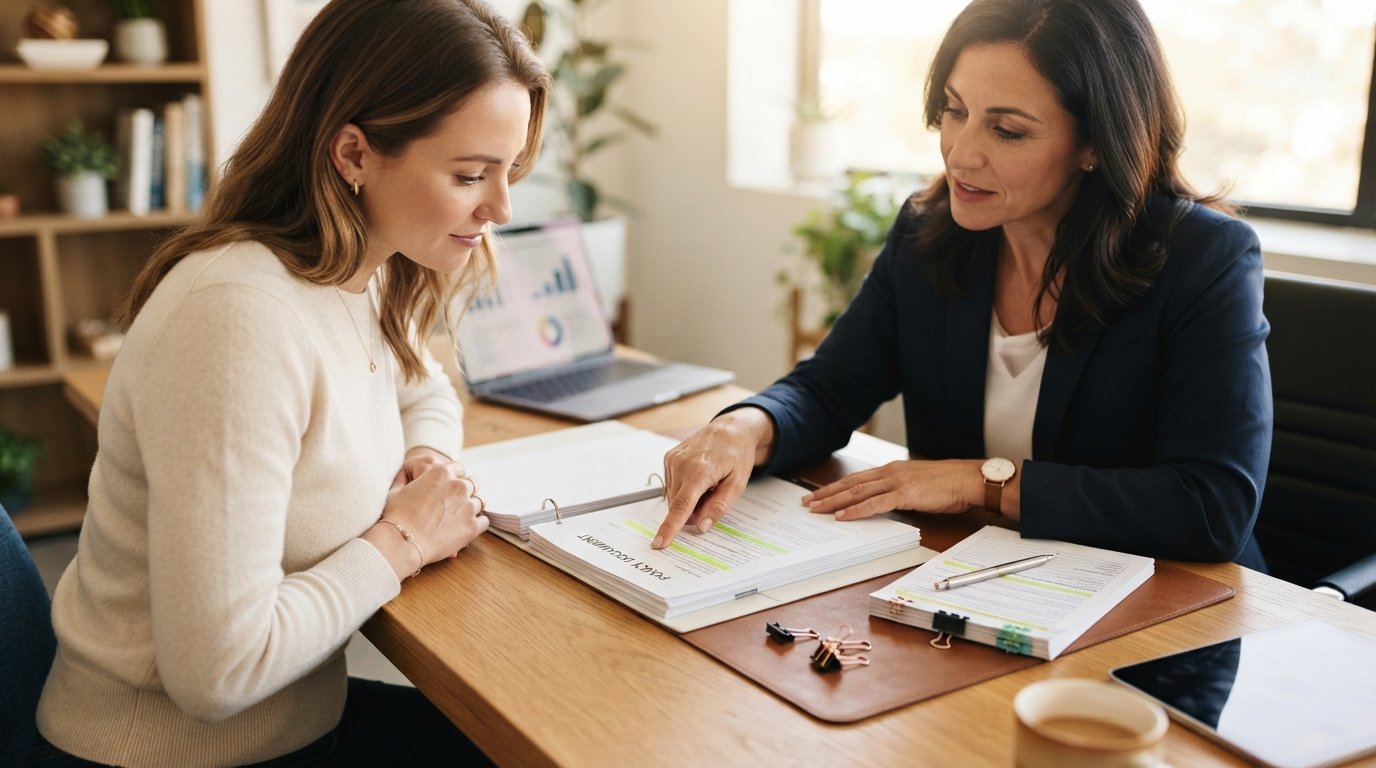
Insurance Riders and Endorsements Explained for Policyholders
Insurance riders and endorsements explained: learn how add-ons customize coverage and can prevent surprise gaps. Call (833)-214-6397 for expert help.
By Caleb Nguyen
Your standard insurance policy is a starting point, not a final destination. Whether you hold a life, home, health, or auto policy, the base contract rarely covers every possible risk or matches your exact situation. That is where riders and endorsements come in. These flexible add-ons let you tailor coverage, close gaps, and avoid paying for protections you do not need. Understanding how they work can save you money and prevent unpleasant surprises at claim time. This guide breaks down insurance riders and endorsements explained in plain terms, with practical examples across major policy types.
What Are Insurance Riders and Endorsements?
An endorsement (sometimes called a rider) is a written amendment to an insurance policy that changes the terms of the original contract. It can add coverage, remove coverage, increase or decrease limits, or clarify how a provision applies. In practice, the two terms are often used interchangeably, though there are subtle differences. "Rider" is more common in life and health insurance, while "endorsement" is typical in property and casualty lines like home and auto. Regardless of the label, the function is the same: customize the policy to fit your needs.
The base policy is the standard contract the insurer offers to everyone in a given class. It is designed to be broad enough for the average customer but not so broad that it becomes unaffordable. Riders and endorsements allow you to adjust that baseline without buying an entirely separate policy. For example, a standard homeowners policy may exclude earthquake damage; an endorsement can add it back. A term life policy may pay a fixed death benefit; a rider can add an accelerated benefit for chronic illness. The key is that the endorsement becomes part of the policy and is subject to its terms, conditions, and exclusions.
It is important to note that not every insurer offers every rider, and availability can vary by state. Some endorsements are standardized by insurance regulators, while others are proprietary to a specific company. When you request a quote, ask which riders are available and how they affect the premium. The following sections explore common examples across life, home, auto, and health insurance, and explain how riders influence costs and administration.
Common Riders and Endorsements Across Insurance Types
Riders and endorsements appear in nearly every line of insurance. Their specific names and features differ, but the underlying principle is consistent: they modify the base contract. Below are examples across four major categories.
Life Insurance Riders
Life insurance riders are perhaps the most well-known. They allow policyholders to add benefits that address specific concerns beyond the death benefit. A few common ones include:
- Accelerated death benefit rider: Lets you receive a portion of the death benefit early if you are diagnosed with a terminal illness. The remaining amount goes to beneficiaries later.
- Waiver of premium rider: Waives premiums if you become totally disabled and cannot work, keeping the policy in force without out-of-pocket cost.
- Child term rider: Provides a small term life benefit for each eligible child, often convertible to permanent coverage later.
- Guaranteed insurability rider: Allows you to purchase additional coverage at set intervals without a new medical exam, useful if your health changes.
These riders can be valuable, but they usually increase the premium. Some are inexpensive, while others (like accelerated death benefits) may be included at no extra cost by certain carriers. Always compare the cost of the rider against the cost of a separate policy that provides similar protection. For instance, a child term rider may be cheaper than buying individual policies for each child, but it may also have limitations on conversion.
Home Insurance Endorsements
Standard homeowners policies typically cover the dwelling, personal property, liability, and additional living expenses. However, they often exclude certain perils or cap coverage for high-value items. Endorsements fill those gaps. Common examples include:
- Scheduled personal property endorsement: Lists specific items like jewelry, art, or collectibles and provides broader coverage (including mysterious disappearance) than the standard policy limits.
- Water backup endorsement: Adds coverage for damage caused by water backing up through sewers or drains, which is usually excluded.
- Ordinance or law endorsement: Pays for the extra cost of rebuilding to current building codes after a covered loss.
- Earthquake endorsement: Adds coverage for earthquake damage, which is excluded in most standard policies.
These endorsements are particularly relevant for homeowners in regions prone to specific risks. For example, a homeowner in California may need an earthquake endorsement, while someone in a flood-prone area might need a separate flood policy (which is not typically an endorsement but a standalone policy through the National Flood Insurance Program or a private insurer). When comparing home insurance quotes, ask which endorsements are available and whether they are included or cost extra.
Auto Insurance Endorsements
Auto policies can also be customized with endorsements. While many auto coverage options are built into the policy (like collision and comprehensive), endorsements address specific needs. Examples include:
- Rental reimbursement endorsement: Pays for a rental car while your vehicle is being repaired after a covered claim, often up to a daily limit.
- Roadside assistance endorsement: Covers towing, jump-starts, lockout service, and flat tire changes.
- Gap coverage endorsement: Pays the difference between what you owe on a car loan and the actual cash value of your vehicle if it is totaled.
- Custom equipment endorsement: Covers aftermarket modifications like custom wheels, audio systems, or lift kits that exceed standard policy limits.
These endorsements are usually inexpensive and can be added at policy inception or renewal. They are especially useful for new car buyers (gap coverage) or those who rely on their vehicle for work. As with any add-on, evaluate whether the extra premium is worth the protection. For example, if you have an emergency fund that could cover a rental car, you might skip rental reimbursement.
Health Insurance Riders
Health insurance riders are less common today because most comprehensive plans cover a broad range of services. However, they still exist in certain contexts, such as short-term health plans or supplemental policies. Examples include:
- Cancer rider: Pays a lump sum upon diagnosis of cancer, which can be used for any purpose.
- Hospital indemnity rider: Pays a fixed daily benefit for hospital stays, helping with out-of-pocket costs.
- Dental or vision rider: Adds coverage for routine dental or vision care that may be excluded from a major medical plan.
These riders are often sold as standalone policies rather than true endorsements to major medical coverage. If you are considering a health insurance rider, read the fine print carefully. Some riders have waiting periods, benefit limits, or exclusions that reduce their value. Also, note that under the Affordable Care Act, essential health benefits cannot be excluded, so riders are more relevant for supplemental coverage.
How Riders Affect Premiums and Policy Administration
Every rider or endorsement has a price, and that price is reflected in your premium. The cost depends on the type of rider, the amount of additional coverage, your risk profile, and the insurer's pricing model. Some riders are relatively cheap (e.g., roadside assistance), while others can significantly increase your premium (e.g., a guaranteed insurability rider on a life policy). It is essential to understand the cost-benefit tradeoff before adding a rider.
From an administrative standpoint, adding a rider means the insurer must update your policy documents, adjust billing, and ensure the endorsement is properly recorded. This is usually straightforward, but it can introduce complexity. For example, if you add a rider mid-term, the insurer may prorate the premium for the remaining months. If you remove a rider, you may receive a partial refund. Always request a copy of the amended policy or a written endorsement to confirm the change. Mistakes can happen, and you want to ensure your coverage is what you expect.
Another administrative consideration is that riders can affect claims handling. When you file a claim, the adjuster will review the base policy and any endorsements to determine what is covered. If a rider was added but not properly documented, the claim could be denied. That is why it is crucial to keep records of all policy changes and review your declarations page annually. The declarations page summarizes your coverage, including endorsements, and is a quick reference for what you have.
When to Choose a Rider Over Separate Coverage
Deciding whether to add a rider or buy a separate policy depends on several factors: cost, convenience, coverage limits, and your overall insurance strategy. A rider is often more convenient because it is attached to your existing policy, so you have one bill and one renewal date. It can also be cheaper than a standalone policy, especially for small add-ons. However, separate coverage may offer higher limits or broader protections that a rider cannot match.
Consider these guidelines when making the choice:
- Choose a rider when: the additional coverage is relatively small, you want simplicity, and the rider is competitively priced. For example, a scheduled personal property endorsement for a $5,000 ring is usually simpler than a separate floater policy.
- Choose separate coverage when: you need high limits, the rider is expensive relative to a standalone policy, or the risk is significant enough to warrant dedicated underwriting. For instance, if you own multiple rental properties, a separate landlord policy may be more appropriate than endorsing a homeowners policy.
- Consider bundling: Some insurers offer discounts if you add riders or bundle policies. Compare the total cost of the rider plus any discounts against the cost of separate coverage.
It is also wise to review your needs annually or after major life events (marriage, new child, home purchase, retirement). A rider that made sense five years ago may no longer be necessary, or you may need new ones. For personalized guidance on comparing policies and riders, you can consult resources like InsuranceAdvisers, which offers educational content and tools to help consumers make informed decisions. Their platform can help you understand how riders fit into your overall insurance plan and connect you with agents who can provide quotes.
Remember that insurance is a product you buy to transfer risk. Riders and endorsements are tools to fine-tune that transfer. They are not inherently good or bad; they are simply options. The key is to align your coverage with your actual exposures and budget. By understanding how riders work, you can avoid overpaying for unnecessary add-ons and ensure you have the protection you need when it matters most.