
Insurance for Self Employed: Health, Auto, Home Guide
Secure health, auto, and home coverage as a self-employed worker. Call (833)-214-6397 for expert help finding the right policies.
By Isaac Ellis
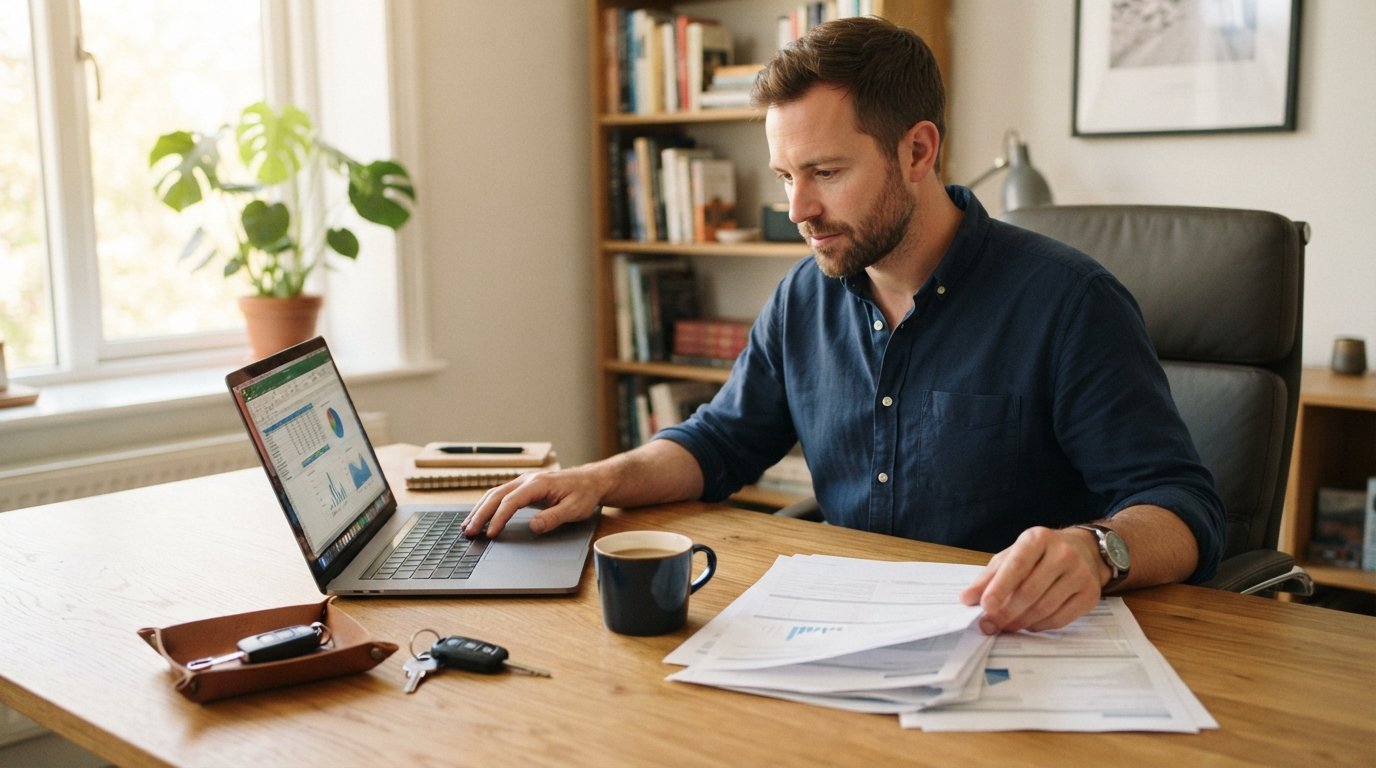
When you are self-employed, you become your own benefits department. There is no employer-sponsored health plan, no HR team to explain your auto policy, and no corporate risk manager to warn you that your home office might not be covered. The freedom of working for yourself is real, but so is the responsibility of protecting your income, your family, and your assets. This guide breaks down insurance for self employed individuals health auto home so you can make confident, cost-effective decisions without wasting hours on hold or overpaying for gaps you do not need.
Why Insurance for Self Employed Individuals Health Auto Home Requires a Different Approach
Traditional employees often receive health coverage, workers compensation, and liability protection through their employer. Self-employed workers must assemble that safety net piece by piece. The stakes are higher because a single uninsured medical event, car accident, or lawsuit can wipe out savings and derail a business. At the same time, you have more control over how you structure coverage, which means you can often find smarter combinations that cost less than buying every policy separately.
Start by mapping your risks. Health insurance protects your body and your finances from medical bills. Auto insurance protects you on the road, especially if you use your vehicle for business. Home insurance protects your property and personal liability, but it may exclude business activities. Beyond these three, consider life insurance if others depend on your income and disability insurance if a prolonged illness would stop you from working. The goal is not to buy every product on the market but to close the gaps that matter most for your situation.
Health Insurance Options for the Self-Employed
Health coverage is usually the biggest concern for newly self-employed individuals. Without an employer subsidy, you are responsible for the full premium, but you still have several paths to coverage. The right choice depends on your income, family size, location, and how much you value network flexibility.
Affordable Care Act Marketplace Plans
ACA marketplace plans are a common starting point. They must cover essential health benefits, cannot deny you for pre-existing conditions, and may offer premium tax credits based on your household income. If your income fluctuates, estimate carefully: too high an estimate reduces your subsidy, while too low an estimate can lead to repayment at tax time. Marketplace plans come in metal tiers (Bronze, Silver, Gold, Platinum) that balance premiums against out-of-pocket costs. Silver plans often make sense if you qualify for cost-sharing reductions.
Private Individual and Family Plans
Outside the marketplace, private insurers offer individual and family policies. These plans may have narrower networks or different benefit designs. They can be a good fit if you do not qualify for subsidies or if you need a specific doctor or hospital. Always read the exclusions and check prescription formularies before enrolling.
Group Alternatives for Small Businesses
If you have employees or partners, you may be able to form a small group health plan. Some states also allow sole proprietors to join association health plans or cooperatives. These options can pool risk and administrative costs, but they vary widely by state and industry. Compare total costs, not just premiums, and confirm that the plan is licensed in your state.
When comparing health plans, use the same framework you would for any major purchase: list your must-have doctors and medications, estimate your annual usage, and calculate total annual cost (premiums plus out-of-pocket maximum). For a deeper dive into plan terminology, see our common insurance terms glossary for beginners.
Auto Insurance When Your Car Doubles as a Work Vehicle
Many self-employed people use a personal vehicle for business errands, client visits, or deliveries. Your personal auto policy may not cover business use, and a claim could be denied if the insurer determines the vehicle was being used for business purposes. The first step is to review your policy's definition of business use and disclose your usage to your insurer.
If you use your car primarily for work, consider a commercial auto policy. If you only occasionally use it for business, a business-use endorsement on your personal policy may suffice. Rideshare and delivery drivers often need a specific endorsement or a commercial policy because personal policies typically exclude paid driving. Keep records of mileage and usage; insurers may ask for them at claim time.
Bundling auto with home or renters insurance can unlock discounts, but bundling does not automatically solve business-use gaps. You still need to confirm that each policy covers how you actually use your vehicle and property. Ask your agent directly: "Does this policy cover business errands and client meetings?" Get the answer in writing if possible.
Home Insurance and the Home Office Gap
If you work from home, your homeowners or renters policy likely covers your dwelling and personal property, but it may exclude business equipment and business liability. A standard policy might cap coverage for business property at a low amount, and it may not defend you if a client sues over work performed in your home. This is one of the most common gaps for self-employed individuals.
Options to close the gap include a home office endorsement, a business owners policy (BOP), or a separate commercial liability policy. A BOP often bundles general liability with property coverage for small businesses and can be cost-effective. If you have inventory, expensive equipment, or client visits, a BOP is worth pricing. If you only have a laptop and occasional client calls, an endorsement may be enough.
Also consider liability for products or services you sell. General liability insurance can cover third-party bodily injury and property damage claims. Professional liability (errors and omissions) covers claims that your advice or service caused financial harm. These are separate from home insurance and are often overlooked until a client dispute arises.
Life and Disability Income Protection
Health, auto, and home insurance protect specific assets, but they do not replace your income if you die or become disabled. If others rely on your earnings, term life insurance is often the most affordable way to provide a safety net. Term policies cover a set number of years and pay a death benefit if you pass away during the term. Permanent life insurance costs more but can build cash value; most self-employed workers start with term and reassess later.
Disability insurance replaces a portion of your income if illness or injury prevents you from working. Self-employed individuals often have no sick leave or employer-provided disability benefits, so this coverage can be critical. Look for policies that define disability in a way that matches your occupation, and check the elimination period (how long you wait before benefits start) and benefit period. Short-term disability may be available through private insurers, while long-term disability can provide income for years.
When budgeting, prioritize health insurance first, then auto and home coverage required by law or mortgage, then disability and life insurance based on dependents and financial obligations. A licensed agent can help you sequence purchases so you are not overwhelmed.
Working with Agents and Comparison Tools to Bundle Coverage
You do not have to become an insurance expert to get this right. Comparison tools and independent agents can save time and reveal discounts you might miss. Start by gathering quotes for health, auto, and home from multiple carriers. Use the same coverage limits and deductibles so you are comparing apples to apples. Then ask about bundling discounts, safe driver discounts, and home security discounts.
Independent agents represent multiple insurers and can explain trade-offs. Captive agents represent one company and may offer deeper knowledge of that company's products. Both can be useful; the key is to ask about business-use exclusions and home office coverage explicitly. For a broader resource that connects consumers with insurance information and providers, you can explore insurance shopping resources to compare options in one place.
Here is a simple process to follow:
- List your coverage needs: health, auto, home, life, disability, and any business liability.
- Gather current declarations pages and note limits, deductibles, and exclusions.
- Request quotes from at least three carriers or use a comparison tool.
- Ask each agent how business use of your car and home office are treated.
- Choose a combination that closes critical gaps and fits your budget, then review annually.
After you enroll, set a calendar reminder to review your policies every year or after major life changes (marriage, new home, new vehicle, hiring employees). Premiums and coverage needs shift, and a quick review can catch gaps before they become claims disputes.
Frequently Asked Questions
Can I deduct insurance premiums as a self-employed business expense?
Some premiums may be deductible, but the rules depend on the type of insurance and your business structure. Health insurance premiums may be deductible for self-employed individuals under certain conditions. Auto and home insurance deductions are usually limited to the business-use portion. Consult a tax professional for your specific situation.
Do I need workers compensation insurance if I am self-employed?
Requirements vary by state and industry. Some states require workers compensation for certain self-employed individuals, especially in construction. Even if not required, it can provide valuable coverage for job-related injuries. Check your state's rules.
What happens if I underestimate my income for marketplace subsidies?
You may have to repay some or all of the subsidy when you file taxes. To avoid surprises, report income changes to the marketplace promptly and update your estimate. Keeping a cushion in your budget for potential repayment is wise.
Insurance for self employed individuals health auto home does not have to be a maze. By understanding the gaps, comparing quotes carefully, and asking direct questions about business use, you can build a protection plan that fits your work and your life.