
Homeowners Insurance: What It Covers and Excludes
Understand what does homeowners insurance cover and exclude, from dwelling to flood gaps. Call (833)-214-6397 for expert guidance.
By Caleb Nguyen
Your home is likely your largest investment, and homeowners insurance is designed to protect it. But many homeowners are surprised to learn that their policy does not cover everything. Understanding what does homeowners insurance cover and exclude is essential to avoiding costly surprises when you file a claim. This guide breaks down the standard coverage, common exclusions, and optional add-ons so you can make informed decisions about your protection.
Standard Homeowners Insurance Coverage: The Four Pillars
Most homeowners insurance policies are written on an HO-3 form, which provides broad coverage for your home and personal property while excluding certain perils. The policy typically includes four main types of coverage: dwelling, other structures, personal property, and liability. Additionally, additional living expenses coverage is often included.
Dwelling Coverage
Dwelling coverage (Coverage A) protects the structure of your home itself, including the walls, roof, floors, and built-in appliances. If a covered peril, such as a fire or windstorm, damages your home, this coverage pays to repair or rebuild it up to the policy limit. The limit is usually based on the replacement cost of your home, not its market value. It is important to review this limit annually to ensure it keeps pace with construction costs.
Other Structures Coverage
Other structures coverage (Coverage B) extends protection to structures on your property that are not attached to your home, such as a detached garage, fence, shed, or swimming pool. The limit is typically set at a percentage of your dwelling coverage, often 10% or more. If you have significant outbuildings, you may need to increase this limit.
Personal Property Coverage
Personal property coverage (Coverage C) protects your belongings, both inside and outside your home. This includes furniture, electronics, clothing, and kitchenware. Coverage is usually provided on a named-perils basis, meaning it covers specific events like fire, theft, or vandalism. However, certain categories of items, such as jewelry, art, and collectibles, have sub-limits that may be much lower than the overall personal property limit. For example, a standard policy might cap theft of jewelry at $1,500. To fully protect high-value items, you may need to schedule them separately or purchase additional coverage.
Liability Coverage
Liability coverage (Coverage E) protects you financially if someone is injured on your property or if you accidentally damage someone else's property. It covers legal expenses, medical bills, and settlements up to the policy limit. Most policies start at $100,000, but experts recommend higher limits if you have significant assets to protect. Liability coverage also typically includes no-fault medical payments to guests who are injured on your property, regardless of fault.
Additional Living Expenses (ALE)
If your home becomes uninhabitable due to a covered peril, additional living expenses coverage (Coverage D) pays for temporary housing, meals, and other increased costs while your home is being repaired. This coverage is usually capped at a percentage of your dwelling limit, such as 20% or 30%. It can be a lifesaver during a lengthy reconstruction process.
What Homeowners Insurance Excludes: Common Gaps
Standard homeowners policies exclude certain perils and situations. Understanding these exclusions is critical because you may need to purchase separate coverage or endorsements to fill the gaps.
Floods
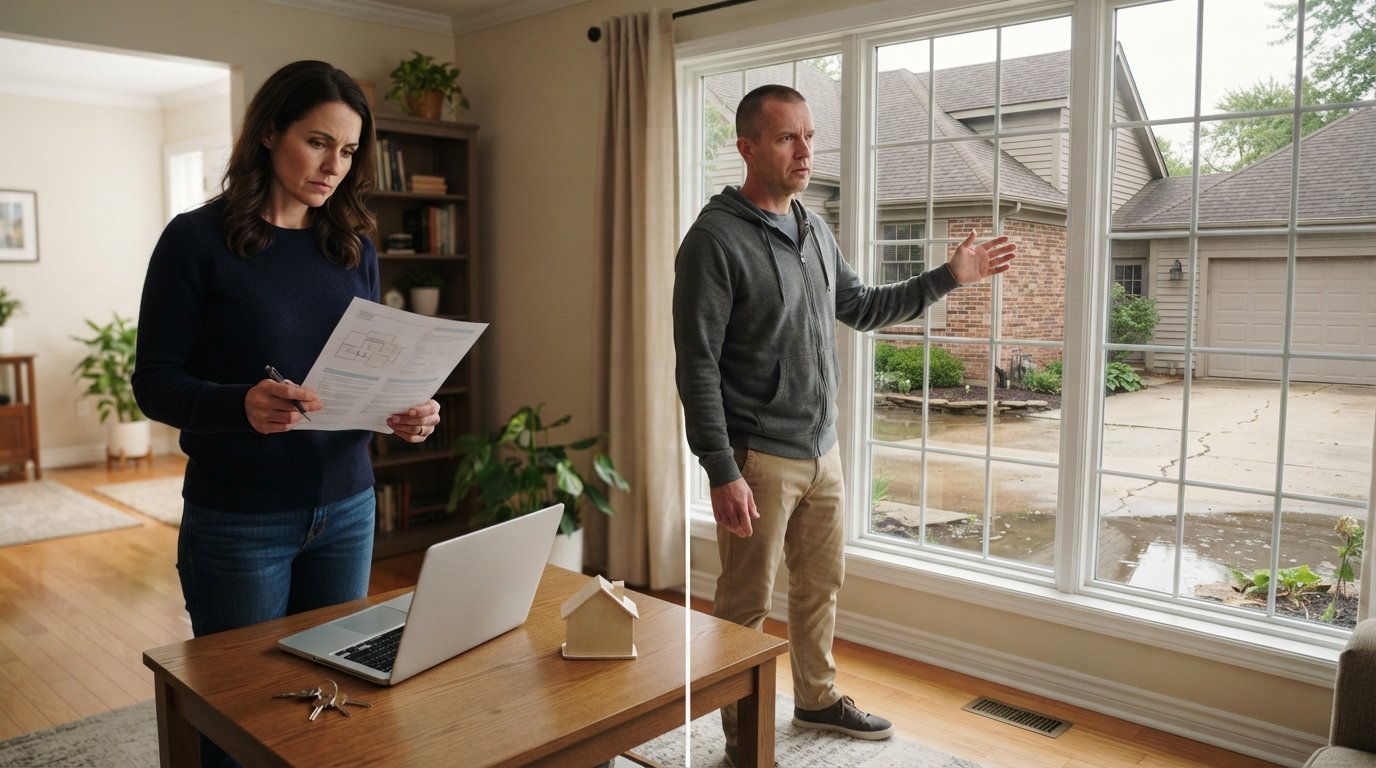
Flood damage is excluded from standard homeowners insurance. This includes damage from rising water, storm surge, and mudslides. To protect against floods, you need a separate flood insurance policy, often available through the National Flood Insurance Program (NFIP) or private insurers. Many homeowners mistakenly believe their policy covers flooding, only to discover the gap after a disaster.
Earthquakes
Earthquake damage is also typically excluded. If you live in a seismically active area, you may need to purchase a separate earthquake policy or add an endorsement to your homeowners policy. Some states, like California, have specialized earthquake insurance options.
Normal Wear and Tear
Homeowners insurance is designed for sudden and accidental damage, not for maintenance issues. Normal wear and tear, deterioration, and neglect are excluded. For example, if your roof leaks due to age, the repair is your responsibility. Similarly, damage from pests, insects, or rodents is generally not covered.
Other Common Exclusions
- Ordinance or law: Costs to bring your home up to current building codes after a covered loss may be excluded or limited.
- Earth movement: Sinkholes, landslides, and other earth movements are often excluded.
- Power failure: Damage caused by a power outage off your premises is typically not covered.
- Intentional acts: Damage you cause intentionally is not covered.
- Business property: If you run a business from home, business equipment and liability may not be covered.
Review your policy's exclusions carefully. Some exclusions can be addressed with endorsements or separate policies, while others are simply uninsurable.
Optional Endorsements and Riders to Fill Coverage Gaps
If you have valuable items or need protection for specific risks, you can often add endorsements (also called riders) to your homeowners policy. These customize your coverage and can be cost-effective.
Scheduled Personal Property
For high-value items like jewelry, artwork, or collectibles, you can schedule them on your policy. This provides broader coverage, often including mysterious disappearance, and eliminates the sub-limits that apply to standard personal property. You will need to provide appraisals or receipts for these items.
Water Backup and Sump Pump Overflow
Standard policies often exclude water backup from sewers or drains. An endorsement can add this coverage, which is valuable if you have a basement or sump pump.
Replacement Cost vs. Actual Cash Value
Many policies pay actual cash value (ACV) for personal property, which deducts depreciation. You can purchase a replacement cost endorsement to get new-for-old coverage, which is especially important for older items.
Building Code Upgrade Coverage
If your home is older, an ordinance or law endorsement can help cover the extra costs to rebuild to current codes after a covered loss.
Other Endorsements
- Identity theft: Covers expenses related to identity theft.
- Home business: Provides limited coverage for business property and liability.
- Equipment breakdown: Covers damage to appliances and systems due to mechanical failure.
When considering endorsements, weigh the cost against the potential benefit. For high-value items, scheduling is often the best way to ensure full protection.
How Policy Limits and Sub-Limits Apply
Policy limits are the maximum amount your insurer will pay for a covered loss. It is crucial to understand that limits apply per occurrence and per category. Sub-limits are lower caps for specific types of property, such as $1,500 for jewelry theft. These sub-limits can leave you underinsured if you do not purchase additional coverage.
For example, if you have $200,000 in personal property coverage but a $1,500 sub-limit for jewelry theft, and your $5,000 ring is stolen, you will only receive $1,500 (minus deductible) unless you scheduled the ring. Similarly, liability limits may be inadequate if you are sued for a large amount. Umbrella policies can provide additional liability protection beyond your homeowners and auto limits.
Review your policy limits annually, especially after major purchases or renovations. Adjusting your limits and deductibles can also affect your premium. For tips on managing costs, see our guide on ways to lower home insurance costs without cutting coverage.
Filing a Claim: What to Expect
If you experience a covered loss, contact your insurer promptly. Document the damage with photos and receipts, and keep a home inventory to streamline the claims process. Understand that filing a claim may affect your future premiums, so weigh the cost of repairs against your deductible. For major losses, the claim process can be complex, and having the right coverage makes a difference.
To compare homeowners insurance quotes and find the right coverage for your needs, visit InsuranceAdvisers. Their resources can help you understand your options and connect with providers.
Homeowners insurance is a vital financial safety net, but it is not all-encompassing. By knowing what is covered and what is excluded, you can close gaps with endorsements or separate policies. Regularly review your policy with your agent to ensure it meets your changing needs and provides the protection you expect.